When InterNations published their 2024 Expat Insider survey — 52 countries, thousands of respondents — Spain didn't just place well. It ranked first globally for quality of life. Valencia, Málaga, and Alicante claimed three of the top spots for overall expat satisfaction, with respondents praising the climate, recreational opportunities, and something Canadians rarely experience: the genuine ease of making local friends.
The appeal goes well beyond sangria and sunshine. Spain offers a developed European economy with living costs 30–40% below comparable Canadian cities, a public healthcare system that consistently ranks in the global top ten, and a culture that organizes itself around human wellbeing rather than productivity metrics. The famous Spanish lunch break isn't a quaint anachronism — it reflects a society that has simply made different choices about what life is for.
But here's the catch. Spain's tax authorities take a comprehensive view of your worldwide income once you become resident, and they expect detailed reporting of foreign assets. Canada's departure tax can take a substantial bite from accumulated wealth if you're not prepared. And visa requirements have their own logic. Understanding these realities before you commit is the difference between Spain working financially and Spain becoming an expensive lesson in cross-border tax planning.
The Cost of Living Case
The mathematics are compelling, particularly for anyone fleeing Vancouver or Toronto. But housing only tells part of the story — the gap extends across virtually every spending category.
| Category | Spain (typical) | Canada (major city equivalent) | Notes |
|---|---|---|---|
| 1-bed apartment (mid-tier city) | €600–€1,200/mo | $1,800–$2,500/mo | Valencia, Seville, Alicante vs. Calgary, Ottawa |
| 1-bed apartment (top-tier city) | €1,100–€1,800/mo | $2,200–$3,200/mo | Madrid, Barcelona vs. Vancouver, Toronto |
| Full lunch (menú del día) | €10–€15 | $18–$25 | Starter, main, dessert, drink included |
| Evening tapas + wine | €15–€20/person | $35–$50/person | Neighbourhood restaurant, not tourist trap |
| Monthly groceries (single) | €200–€300 | $400–$600 | Local markets drive the Spanish number down |
| Monthly transit pass | €40–€60 | $100–$160 | Madrid and Barcelona have extensive metro systems |
| Private health insurance | €50–€150/mo | $200–$600/mo | Comprehensive coverage in both cases |
Spain's high-speed rail network connects major cities at prices and speeds that make VIA Rail look like a different century — Madrid to Barcelona in under three hours, Madrid to Seville in two and a half. Many expats find car ownership unnecessary entirely, which is a savings category that doesn't even appear in the table above but adds up to thousands annually when you factor in insurance, maintenance, and fuel.
Healthcare Deserves Its Own Conversation
The Spanish National Health System covers GP visits, specialist consultations, emergency care, hospitalization, maternity services, and most prescriptions with minimal co-payments. Legal residents who contribute to social security get comprehensive public coverage at no additional cost. Canadians accustomed to months-long waits for procedures often find Spain's healthcare surprisingly accessible — and private insurance, required for visa applicants and preferred by many expats for faster specialist access, runs €50–€150 monthly for comprehensive coverage.
The public system handles serious medical needs with excellence. Private insurance adds dental, optical, and faster specialist appointments, but it's a convenience layer, not a necessity for critical care.
Climate Varies More Than You Think
Spain's geography produces dramatically different conditions depending on where you land.
| Region | Summer | Winter | Character |
|---|---|---|---|
| Mediterranean coast (Valencia, Costa del Sol) | Hot, dry | Mild, 10–15°C | 300+ sunny days/year |
| Madrid (continental) | Hotter than the coast | Genuinely cold, occasional snow | Four distinct seasons |
| Northern "Green Spain" (Basque Country, Galicia, Asturias) | Cool, pleasant | Rainy, mild | Pacific Northwest energy |
| Southern Andalusia (Seville, Granada) | Baking, 40°C+ | Europe's warmest winters | Best for cold-averse Canadians |
| Balearic Islands (Mallorca, Ibiza) | Warm, breezy | Mild, 10–14°C | Island life within Europe |
Where Canadians Are Settling
Valencia has emerged as Spain's most popular expat destination for a reason — Mediterranean beaches, a walkable historic centre, world-renowned gastronomy (paella originated here), and living costs 20–30% below Madrid and Barcelona. The city combines genuine affordability with a quality-of-life rating that leads the country.
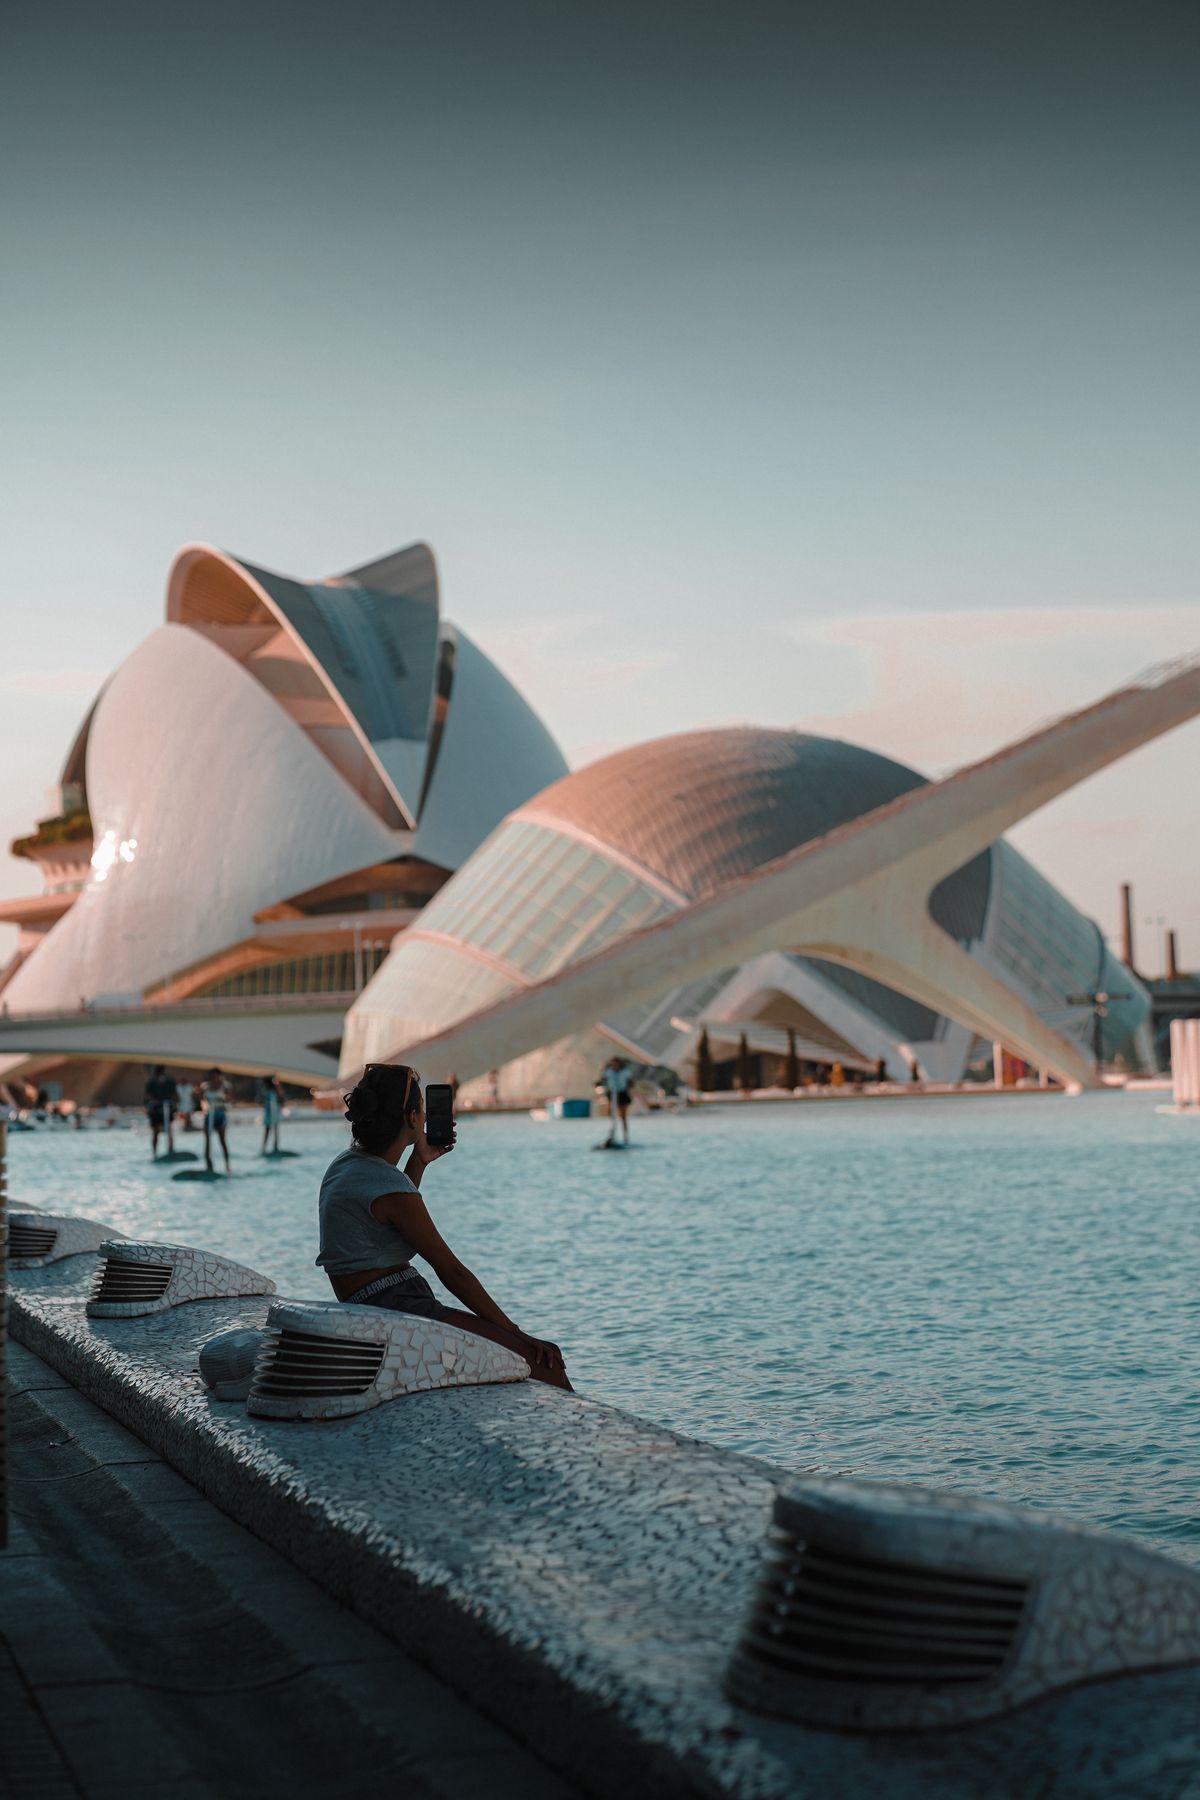
Valencia is attracting a large influx of expats and digital nomads. Photo by Abdulrhman Alkady on Pexels.
Barcelona draws those who prioritize culture, nightlife, and cosmopolitan intensity. It's Spain's most expensive city for housing (central one-bedrooms run €1,400–€1,800 monthly), and the tourist presence reshapes certain neighbourhoods. But for European city life at its most vibrant, very little competes.
Madrid attracts professionals and entrepreneurs. Spain's largest English-speaking community, unmatched cultural institutions, and business connectivity compensate for the absence of beaches. Housing matches Barcelona in the centre but drops significantly in surrounding neighbourhoods with excellent metro access.
Andalusia — Seville, Granada, Málaga, the Costa del Sol — offers Spain's most affordable living combined with its warmest winters. Seville provides authentic Spanish culture at 30% below Madrid prices. Granada adds stunning beauty beneath the Sierra Nevada at even less. Málaga has quietly transformed from sleepy port to vibrant cultural centre.
Northern Spain — the Basque Country, Asturias, Galicia — appeals to Canadians who won't miss Mediterranean heat and want authentic Spanish culture untouched by mass tourism. San Sebastián's gastronomy is world-class. Bilbao has reinvented itself. Smaller cities provide extraordinary value.
Navigating Spain's Visa System
Spanish bureaucracy rewards preparation and punishes improvisation. Canadians get 90 days visa-free within any 180-day period across the Schengen Area — enough for reconnaissance, not enough for legal residence. Overstaying carries serious consequences, including bans on future entry.
The two primary pathways for Canadians:
| Visa | Who it's for | Income requirement | Can you work in Spain? | Key conditions |
|---|---|---|---|---|
| Non-Lucrative | Retirees, financially independent | €2,400/mo primary + €600/mo per dependent | No — no employment or Spanish-sourced business income | Full private health insurance (100% coverage, no co-pays, no deductible) required; initial 1-year, then 2-year renewals |
| Digital Nomad (introduced 2023) | Remote workers for non-Spanish employers | About €2,849/mo (200% of Spain's 2026 minimum wage of €17,094 a year) | Yes — remote work for foreign employers/clients only | Proof of remote employment or freelance contracts, plus the same full health insurance, required |
The health insurance requirement trips up more applicants than the income thresholds do. Spain doesn't accept just any "comprehensive" plan — for both visas the policy must provide 100% coverage with no co-payments and no deductible, broadly equivalent to what the Spanish public system offers, written by an insurer authorized to operate in Spain. Travel policies and ordinary high-deductible plans are routinely rejected. This is also where applicants with pre-existing conditions or a cancer history can hit a wall: insurers may impose waiting periods, exclude the condition, or decline coverage outright — and a policy that carves out your pre-existing condition won't satisfy the consulate. If that's your situation, price and secure the insurance early. It can be the longest part of the application, and occasionally the factor that decides whether the visa is viable at all.
Spain's Golden Visa program was terminated in April 2025.
Regardless of pathway, all long-term residents must obtain a NIE (Número de Identificación de Extranjero) — a foreigner identification number required for virtually all legal and financial transactions — and within 30 days of arrival, apply for a TIE (Tarjeta de Identificación de Extranjero), your physical residence card. The Non-Lucrative Visa grants initial one-year residence, renewable for two-year periods; after five continuous years, you become eligible for permanent residence and eventually Spanish citizenship — a ten-year timeline from arrival to passport for most nationalities.
The Ibero-American Fast-Track
That ten-year timeline shrinks dramatically for Canadians who were born citizens of a Latin American country. Under Article 22(1) of Spain's Civil Code, nationals by origin (nacionales de origen) of any Ibero-American country — Argentina, Bolivia, Brazil, Chile, Colombia, Costa Rica, Cuba, Dominican Republic, Ecuador, El Salvador, Guatemala, Honduras, Mexico, Nicaragua, Panama, Paraguay, Peru, Uruguay, Venezuela — plus the Philippines, Equatorial Guinea, Andorra, and Portugal can apply for full Spanish citizenship after just two years of legal residence. Not permanent residence. Citizenship. An EU passport.
This is particularly relevant for Canadians who originally immigrated from Latin America and are now considering international retirement. A Canadian citizen who was born in Colombia or Peru and still holds that nationality can enter Spain on a Non-Lucrative Visa, complete two years of legal residence, pass the CCSE exam (Spanish culture and constitution — administered by the Instituto Cervantes), and apply for naturalization. Native Spanish speakers are exempt from the DELE A2 language exam as of 2025, which removes another barrier. And Spain's bilateral agreements with Ibero-American nations mean dual citizenship is preserved — no renunciation required.
| Standard pathway | Ibero-American pathway |
|---|---|
| 5 years to permanent residence | 2 years to citizenship eligibility |
| 10 years to citizenship eligibility | Dual nationality preserved |
| Must renounce original nationality (with exceptions) | DELE A2 language exam waived for native Spanish speakers |
| DELE A2 + CCSE exams required | CCSE exam only |
The practical timeline from arrival to passport in hand is closer to 3.5–5 years once you factor in the 12–36 months of Ministry of Justice processing after the two-year residency requirement is met. But compared to the standard decade-long path, it's a fundamentally different proposition — and for a Canadian retiree from Latin America weighing Spain against Portugal or Mexico, it may be the deciding factor.
Spain's Tax System
Here's where most Canadians get surprised, and where a sunny relocation plan starts accumulating line items.
Tax residency triggers when you spend more than 183 days per year in Spain, or when your centre of economic interests or family resides there. Once tax resident, you owe Spanish tax on worldwide income — Canadian pensions, investment returns, rental income from Canadian property, everything. Spain does not have split-year treatment: you're either resident or not for the entire calendar year.
How IRPF Actually Works: State + Comunidad
Spain's personal income tax — the IRPF (Impuesto sobre la Renta de las Personas Físicas) — is not a single federal tax. It's split roughly 50/50 between two layers: the state (estado) sets a progressive scale that applies uniformly across Spain, and each of the 15 common-regime autonomous communities (comunidades autónomas) sets its own regional progressive scale on top. Both layers tax the same income base. Your total IRPF liability is the sum of both, which means where you live in Spain has a direct and potentially large impact on your tax bill.
The state brackets for general income (employment, self-employment, rental income) are:
| Taxable income (€) | State rate |
|---|---|
| Up to €12,450 | 9.5% |
| €12,451–€20,200 | 12% |
| €20,201–€35,200 | 15% |
| €35,201–€60,000 | 18.5% |
| €60,001–€300,000 | 22.5% |
| Over €300,000 | 24.5% |
Those are only the state half. Each comunidad adds its own scale — from 8.5% (Madrid's bottom rate) up to 29.5% (Valencia's top rate). What you actually pay is the combined rate, and the spread between communities is significant. Here's how the combined top marginal rates compare across the comunidades most popular with Canadian expats:
| Comunidad autónoma | Combined top rate | Notes |
|---|---|---|
| Madrid | 45% | Lowest top rate in Spain (regional 20.5% above €57,320); also a 100% wealth tax bonus |
| Andalusia | 47% | Top regional rate of 22.5% applies from €60,000 |
| Balearic Islands | 49.25% | Top regional rate of 24.75% above €175,000 |
| Canary Islands | 50.5% | Top regional rate of 26% above €123,745 |
| Catalonia | 50% | Top regional rate of 25.5% above €175,000 |
| Valencia | 54% | Highest combined top rate in the common regime; regional 29.5% above €200,000 |
Source: Ministerio de Hacienda, Tributación Autonómica 2025, Capítulo IV (regional scales in force for 2025).
The state half is identical everywhere, so the whole difference sits in the regional scale. Above €175,000, every additional euro of general income costs 5 cents more in Barcelona than in Madrid (25.5% versus 20.5% regional), and Catalonia's rates are higher than Madrid's at every level below that too. The gap compounds every year you're resident. For Canadians choosing between Barcelona and Madrid, it's a structural cost of living in one comunidad versus another.
Two regions operate entirely outside this system: the Basque Country (Euskadi) and Navarra have fully independent tax codes under Spain's foral regime (concierto económico). They set their own complete IRPF brackets — not just a regional supplement. Their rates are generally competitive with Madrid but the structures are complex and distinct.
Savings Income: A Separate Scale, No Regional Variation
Investment income — dividends, interest, and capital gains from asset disposals — is taxed on a separate national schedule that's uniform across all common-regime comunidades:
| Savings income (€) | Rate |
|---|---|
| Up to €6,000 | 19% |
| €6,001–€50,000 | 21% |
| €50,001–€200,000 | 23% |
| €200,001–€300,000 | 27% |
| Over €300,000 | 30% |
No regional variation here — a meaningful distinction from general income. All capital gains from selling assets go on this savings scale, however long you held them (Ley 35/2006 del IRPF, art. 46(b)).
Wealth Tax
Spain also levies wealth tax on net worldwide assets above €700,000 for residents (with a primary residence exemption up to €300,000). But this is another area where your comunidad matters enormously. Madrid, Andalusia, Extremadura, Cantabria, and La Rioja grant a 100% bonus on the regional wealth tax (while the national solidarity tax is in force, some of them swap it for a partial bonus so the national tax still applies). Catalonia, by contrast, exempts only the first €500,000. Above €3M, the national Solidarity Tax on Large Fortunes (1.7–3.5%) applies regardless of where you live, so the regional relief has a ceiling.
One exception to all of the above: Spain's Beckham Law (Special Tax Regime for Inbound Workers) offers a flat 24% rate on Spanish-sourced employment income for up to six years, with foreign-sourced income excluded entirely and regional IRPF differences eliminated. It requires qualifying employment or remote work for a foreign employer — so it's relevant to Digital Nomad Visa holders but structurally inapplicable to anyone on a Non-Lucrative Visa living on pensions and investment income.
The Modelo 720
Spanish tax residents must declare foreign assets exceeding €50,000 in any category — bank accounts, securities, real estate. Penalties for non-compliance were reduced following EU court challenges, but the reporting obligation remains. Your Canadian bank accounts, investment portfolios, and properties must all be disclosed to Spanish authorities.
Registered Accounts and Pensions
Spain has two tax bases, and where your Canadian income lands decides the rate. The general base is taxed on the state scale plus your comunidad's scale, up to 54% combined in some regions. The savings base runs from 19% to 30%. Spain's tax authority, the Dirección General de Tributos (DGT), has settled some of this in binding rulings. The rest is genuinely open.
| Income | Spanish base | How settled it is |
|---|---|---|
| CPP and OAS | General (work income, LIRPF art. 17) | Settled — binding rulings V2866-15, V2956-17, V0081-20 |
| Employer pensions (RPP, government service) | General (work income) | DGT treats employment-linked foreign pensions as work income (V2508-21, V0251-25). The treaty's government-service article excludes pensions, so both countries may tax a government pension |
| RRSP / RRIF withdrawals | Probably savings (capital income, art. 25.3) | Open. No ruling classifies them, and V2239-24 declined to. Plans not linked to employment have been ruled savings income (a US Roth IRA, V1291-22; an Australian pension account, V0250-25). The 40% reduction for old Spanish pension plans doesn't apply |
| TFSA | Savings, but when is unsettled | Open. No ruling. Spain treats trusts as transparent, which would tax the income inside a TFSA every year; the Roth IRA ruling taxed only on withdrawal |
| Dividends, interest, gains | Savings | Settled (art. 46) |
Canada still withholds on the same income. Under the treaty (Art. XVIII), Canada's tax on periodic pensions, CPP, OAS and RRIF payments can't exceed 15%, and Spain credits the Canadian tax against its own. But Spain credits only what the treaty allows Canada to take (V0924-23): anything Canada over-withholds is yours to reclaim from the CRA, not from Spain.
Your personal and family minimum doesn't come off your income. Spain taxes it at 0%, subtracting the tax its scale would charge on that amount, starting with the general base (arts. 56.2 and 63). And Spanish residents report foreign accounts and investments over €50,000 per category on Modelo 720, TFSAs and RRSPs included.
The interaction between the two systems demands planning. Getting it wrong means either paying tax twice on the same income or, worse, discovering the problem after you've already structured your affairs in a way that's expensive to unwind.
The Financial Considerations Most Canadians Overlook
Spain's appeal rests on lifestyle and affordability. But Canadians focused solely on Spanish living costs routinely underestimate the financial complexity of leaving Canada itself.
Departure Tax
When you cease to be a Canadian tax resident, the CRA considers you to have sold certain property at fair market value — even if you haven't actually sold anything. This "deemed disposition" triggers capital gains tax on any appreciation that occurred during your Canadian residency. Non-registered investment portfolios, shares in private corporations, real estate outside Canada, valuable personal property — all become potentially taxable upon departure. Canadian real estate (your home and any rental properties) is excluded from the deemed disposition under ITA 128.1(4)(b)(i); you're taxed on it only when you actually sell. Registered accounts like RRSPs are also excluded.
For Canadians who've accumulated significant wealth through real estate appreciation or long-term investments, departure tax can represent a substantial payment due on a departure date you chose. Getting the calculation wrong creates problems in either direction: overpay and you've unnecessarily depleted your retirement funds; underpay and you face interest, penalties, and enforcement action.
Leaving Canada? Let's get it right the first time.
The free tools get you most of the way. For the irreversible decisions, book a 45-minute call and we'll walk through your situation.
Ongoing Canadian-Source Income
Rental income from Canadian property, dividends from Canadian corporations, and pension payments all remain subject to Canadian withholding tax after departure — typically at 25% of gross amounts. The Canada-Spain tax treaty may reduce these rates for certain income types, but claiming treaty benefits requires knowing which provisions apply to your specific situation. Arm's-length interest is the exception: it's paid to non-residents with no Canadian withholding at all. Two elections can also lower the bill. Section 216 lets you file a return on net rental income instead of paying 25% of gross rent. Section 217 lets any non-resident, in Spain or elsewhere, pay tax on CPP, OAS, pensions, and RRIF payments at graduated rates instead of the flat withholding.
Registered Accounts After Departure
You can maintain your RRSP after leaving Canada, but withdrawals face non-resident withholding tax. Contributing to a TFSA while non-resident triggers penalties. Home Buyers' Plan and Lifelong Learning Plan balances come due upon departure. The CRA requires multiple forms documenting your exit, including detailed asset inventories and deemed disposition calculations, and penalties for missing or incomplete filings run to thousands of dollars per form.
Planning Your Departure Properly
Rushing a move to Spain can cost tens of thousands of dollars in unnecessary taxes or penalties. The complexity means timing and preparation are as important as the decision itself.
Asset review and optimization should begin well before your departure date. Understanding which assets will generate gains upon deemed disposition, whether opportunities exist to offset gains with losses, and whether timing adjustments could reduce your overall burden requires analysis done months ahead — not weeks.
Residency severance involves more than changing your mailing address. The CRA examines residential ties (property, family), social ties (memberships, associations), and economic ties (bank accounts, business interests). Maintaining too many Canadian connections can result in continued Canadian tax residency even while you're living in Seville and eating paella three times a week.
Spanish tax planning deserves attention before arrival. How to structure your income timing, which assets to hold where, and whether any special regimes apply to your situation all affect your outcome. The choices you make in your first year can lock in advantages — or disadvantages — for years to come.
Coordination between jurisdictions ties everything together. The Canada-Spain tax treaty determines which country has primary taxing rights on various payment types and how to claim appropriate credits. Navigating both systems simultaneously is the entire game.
Run Your Own Numbers First
Cross-border tax specialists charge hundreds of dollars an hour, and departure planning often takes several consultations. Expatify is built for Canadians who want to understand their numbers before they start writing those cheques — every calculator below is free, with no sign-up.
| Free tool | What it does |
|---|---|
| Departure tax calculator | Estimates your deemed-disposition liability based on your actual assets |
| Expat income tax calculator | Models Canadian withholding and Spanish tax on your Canadian income, with treaty rates, foreign tax credits, and the Section 217 option |
| Compare countries | Ranks destinations, Spain included, by how much of your income you'd keep after tax |
| Tax residency checker | Walks through the residential ties the CRA weighs when deciding whether you've actually left |
| Leaving-Canada checklist | Organizes the whole process by timeline — twelve months out through post-departure — so nothing slips |
If you'd rather talk it through, you can also book a one-on-one call.
Making the Decision
Spain offers Canadians something increasingly precious: a genuinely different way of living that doesn't require sacrificing comfort or security. Affordable costs, excellent healthcare, rich culture, and a quality of life that Canada's expensive cities simply cannot match.
But the move requires more than enthusiasm. Canada's tax system is designed to capture the gains you've accumulated during residency, and Spain's comprehensive approach to taxing residents adds layers of complexity that demand attention. The Canadians who thrive in Spain are those who approached the transition thoughtfully — understanding their obligations, planning accordingly, and avoiding the surprises that derail less-prepared expats.
Whether you're seriously planning a move, casually exploring, or simply curious about what leaving Canada would involve, understanding your departure tax obligations is where the journey properly begins. The numbers might confirm that Spain makes financial sense — or they might reveal that adjustments to your timeline or asset structure would serve you better. Either way, you'll be making decisions based on reality rather than assumptions.
Ready to understand what leaving Canada would cost you? Start with the departure tax calculator and get a clear picture of your obligations before you make any decisions.
Related Resources:
- CRA: Leaving Canada (Emigrants)
- Canada-Spain Tax Convention and its 2014 Protocol
- Spanish Consulate Toronto: Non-Lucrative Visa
Free Tools & Calculators:
- Canadian Departure Tax Calculator
- Expat Income Tax Calculator
- Compare Countries
- Tax Residency Checker
- Leaving-Canada Checklist
This content is for educational purposes and reflects information current as of October 2026. Tax rates, visa requirements, and government programs change — verify details with the relevant authorities before acting. Individual circumstances vary, and cross-border tax situations benefit from professional guidance.